

Today’s topline inflation number, as measured by the Bureau of Economic Analysis’ Personal Consumption Expenditure (PCE) data, came in as forecasters expected, indicating that inflation is currently at 2.2% over the last twelve months. Viewed in isolation, one might expect forecasters to celebrate, markets to boom, and the Fed to rush to cut rates. But none of that is happening. Why? President Trump’s chaotic tariff agenda is injecting huge amounts of uncertainty and pessimism into our economy – jeopardizing long-term progress on inflation. As one reporter tweeted, “If not for the broad imposition of tariffs that threaten to set back this improvement, this report would be getting high fives.” President Trump’s chaotic tariff agenda means economic uncertainty is the new norm, jeopardizing the progress we’ve made on inflation.
Senator Warren highlighted this dynamic in her statement this morning:
“President Trump is not serious about lowering costs for Americans. Multiple courts have now found his chaotic, across-the-board tariffs to be unlawful – and his policies are hurting families and businesses across the country. When Trump came into office, inflation was on a clear downward trajectory. Today, businesses are signaling their intention to raise prices even more in response to Trump’s tariffs. Economic forecasters are predicting both slower growth and renewed inflationary pressure. This week’s jobless claims underscore how policy uncertainty is also weakening the labor market. Americans deserve lower interest rates that would make life more affordable, but, let me be clear, Trump and Republicans in Congress are the reason the Fed can’t bring rates down.” – Senator Warren
Digging into today’s PCE print highlights why some of the concerns under the hood of the report continue to fuel pessimism among experts.
I. Consumer spending
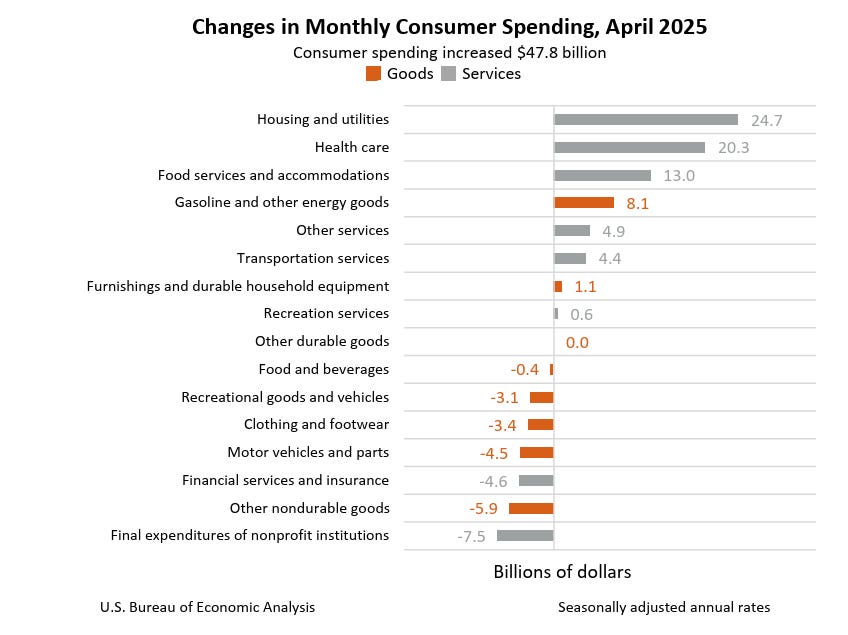
Consumer spending accounts for 70% of GDP. Sustained weakness in this metric could have meaningful implications for overall economic growth. In that context, it is worrisome that real spending slowed to 0.2% growth in April, down from March’s 0.7% increase. That’s a notable deceleration in consumer activity, and extends a pattern evident in the revised Q1 2025 data (where real spending growth was adjusted downward from 1.8%to 1.2%). The softening in real spending aligns with survey data suggesting increased consumer caution about future economic conditions, potentially indicating a shift toward more conservative spending behavior. Spending on goods – which is particularly likely to be affected by tariffs, “softened amid cutbacks on purchases of motor vehicles and parts, clothing and footwear as well as recreational goods and vehicles.”
II. Income
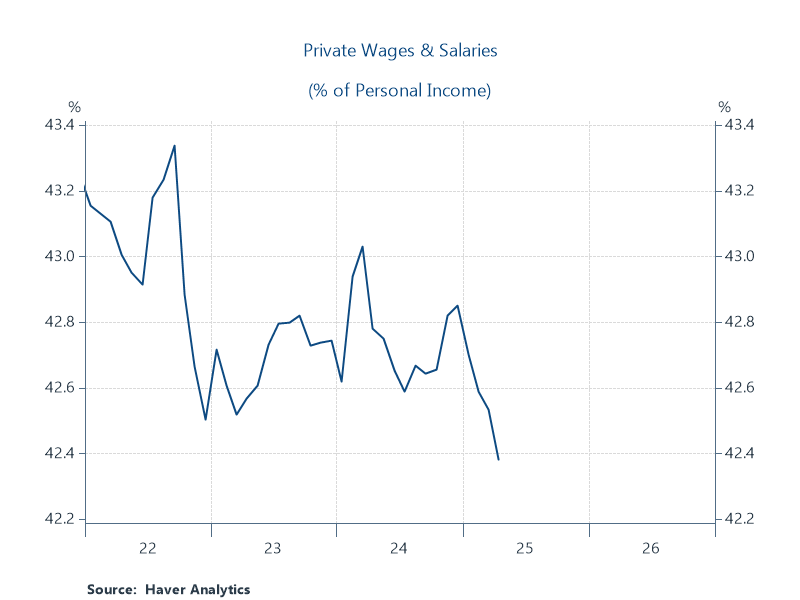
Real disposable income maintained 0.7% growth in both March and April. The composition of these gains, however, suggests a potentially important and concerning structural shift. Government transfers, including Social Security, Medicare, and Medicaid, stand out as primary drivers of this income growth. Private sector contributions, by comparison, have moderated. Renaissance Macro Research points out, “[p]rivate wages and salaries represent 42.4% of personal income, which is the lowest since 2021, when pandemic relief payments were surging.” This changing income mix normally follows a significant economic slowdown, so it’s particularly concerning to see now, at a time when unemployment remains relatively low. It raises questions about long-term sustainability of income gains – and that’s before one considers the Trump Administration’s “big, beautiful bill” proposal, which would slash government transfer programs and is projected by the Congressional Budget Office to actually cause a decline in the disposable incomes of most Americans.
III. Durable goods inflation
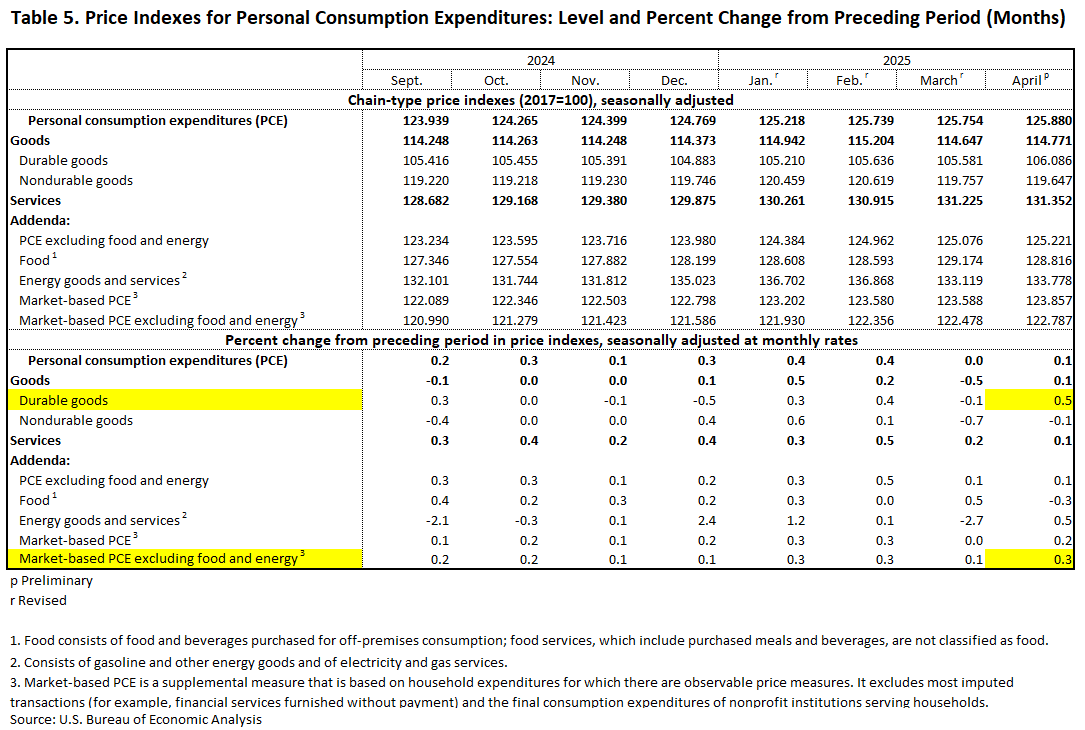
Price pressures in durable goods (which include long-lasting items like cars, appliances, furniture, and electronics that consumers typically keep for several years) are becoming more evident, with inflation in this category rising 0.5% in April—the highest monthly increase since September 2022. Another measure of core goods inflation, which excludes food and energy, also accelerated to 0.3% for the month. These categories are typically most sensitive to import price changes. The acceleration of these categories above and beyond this months’ broader inflation measures is an indication that companies may be beginning to incorporate higher import costs (or higher expected import costs) into the prices they charge for goods.
IV. Jobs
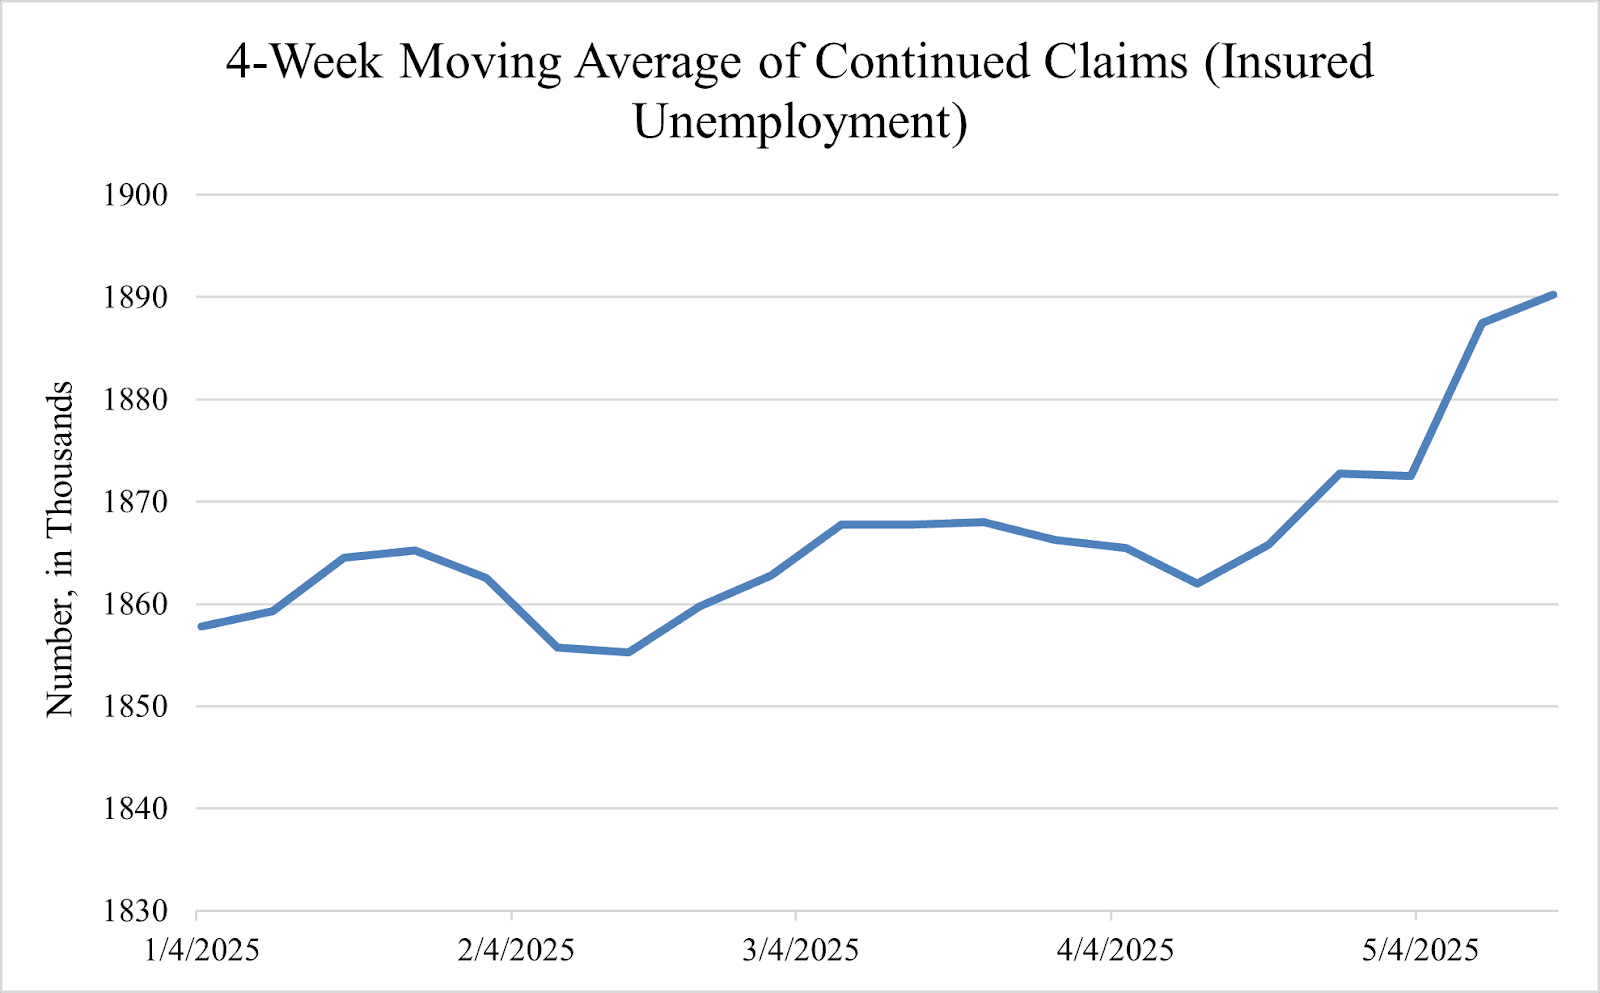
Finally, this week’s jobless claims data hints at expanding potential weaknesses in the labor market. Initial jobless claims ticked up, and recurring job applications increased to its highest level since November 2021. One Bloomberg report noted that “[t]he numbers suggest the combined impact of the Trump administration’s trade policy and government spending initiatives are starting to take a larger toll on the labor market as those out of work increasingly struggle to find new positions.” A weakening labor market and cooling inflation would normally signal to the Fed that they should ease interest rates. But as we have discussed before, the trade and economic policies currently being pursued by the Trump Administration and Republicans in Congress have put the Fed in a vise that precludes the Fed from effectively using monetary policy to address these growing problems.